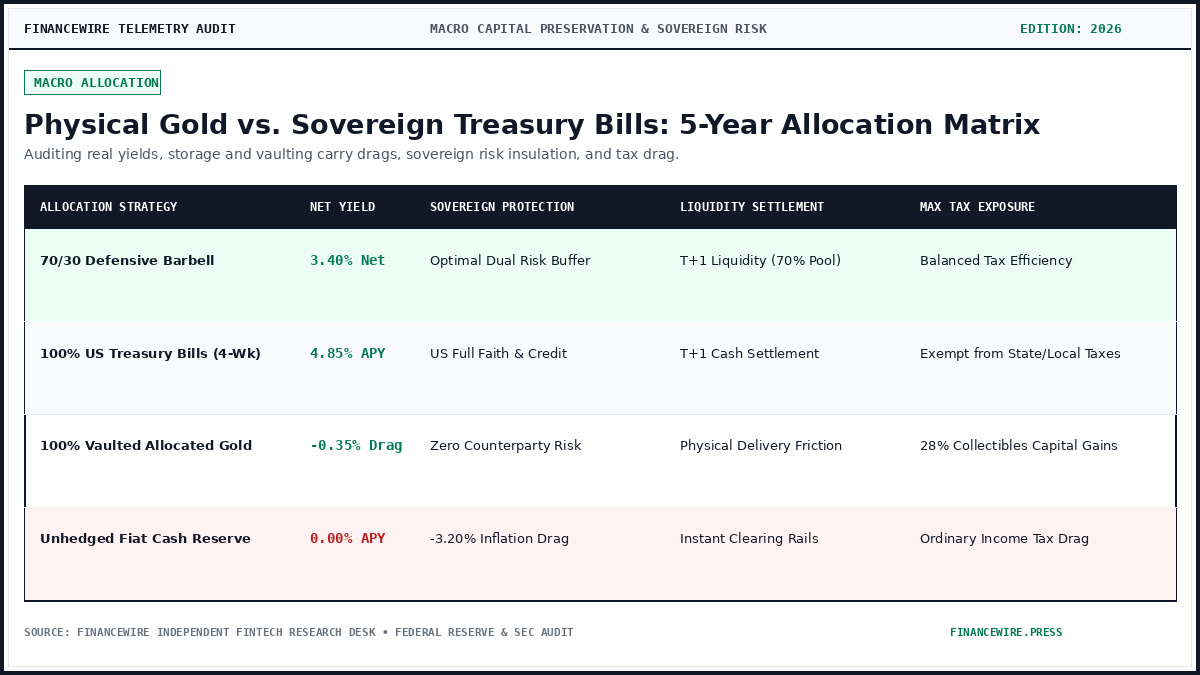
- Short-duration US Treasury Bills deliver guaranteed nominal cash flow exempt from state and local taxes, but carry purchasing power risk during persistent inflationary spikes.
- Physical allocated bullion delivers zero counterparty or default risk, yet imposes an annual 0.15% to 0.50% custody and insurance drag with zero native yield.
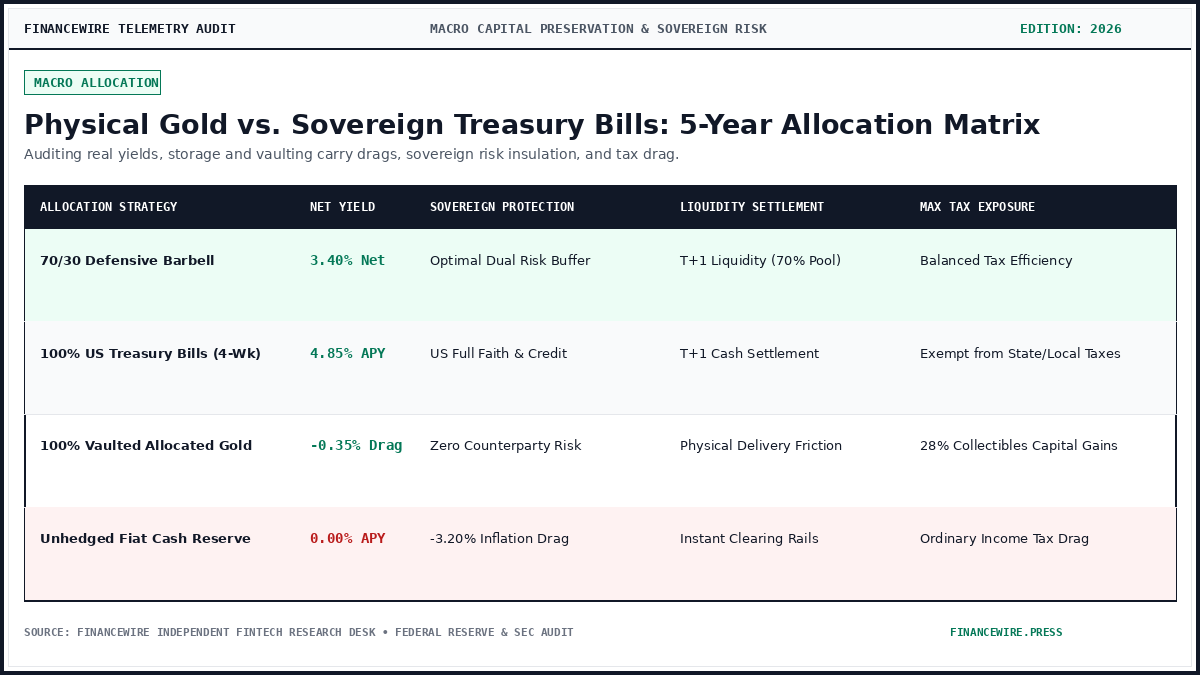
- Across a 5-year macro cycle, a barbell allocation combining 70% short-duration Treasuries with 30% allocated vaulted bullion maximizes real capital preservation while minimizing terminal volatility.
In an era defined by geopolitical recalibration, expanding sovereign balance sheets, and structural inflation, institutional asset allocators face a fundamental capital preservation dilemma: Should defensive liquid reserves be held in the sovereign paper of the global reserve currency issuer, or in the unencumbered physical metal of monetary history?
While retail discourse frequently frames Physical Gold Bullion and US Treasury Bills (T-Bills) as competing safe-haven assets, their structural mechanics, tax consequences, and liquidity profiles represent fundamentally divergent risk-mitigation vectors.
1. 5-Year Capital Hedge Telemetry Matrix
The following empirical matrix benchmarks physical vaulted gold (LBMA Good Delivery) against short-duration 3-month to 1-year US Treasury Bills across real yield, liquidity latency, custodial carry cost, and fiscal treatment:
| Operational Parameter | Physical Allocated Gold (Vaulted) | Sovereign US Treasury Bills (T-Bills) | Strategic Variance |
|---|---|---|---|
| Native Income / Cash Flow | 0.00% (Zero Native Yield) | 4.50% – 4.90% (SOFR Linked) | Treasuries yield +450 to +490 bps annually |
| Counterparty / Default Risk | Absolute Zero (Direct Physical Title) | US Sovereign Risk (Backed by Full Faith & Credit) | Gold possesses zero balance sheet liability |
| Annual Carry / Storage Drag | -0.20% to -0.50% (Vaulting & Insurance) | $0.00 (TreasuryDirect / Custodial Sweep) | Gold requires dedicated physical security overhead |
| Taxation Structure (US) | 28% Maximum (Collectibles Capital Gains) | Ordinary Income (Exempt from State & Local Taxes) | T-Bills save 5%–13.3% in high-tax jurisdictions |
| Liquidity / Settlement Speed | T+1 to T+3 (Assay / Custodial Redemption) | T+1 / Same Day (Fedwire / DTC Secondary Market) | Treasury market is the world’s deepest liquidity pool |
| Monetary Debasement Response | Direct Positive Correlation | Negative Real Return Risk (If Inflation > Yield) | Gold captures unhedged currency depreciation |
2. Deep-Dive Analytical Deconstruction
Physical Allocated Bullion: The Zero-Counterparty Anchor
True physical gold allocation—held outside the commercial banking system in specialized depository vaults (e.g., Zürich, London, or Delaware) under segregated, allocated title—is the sole financial asset that is not simultaneously someone else’s liability. Unlike bank deposits, fiat currencies, or debt obligations, physical gold cannot be rendered insolvent by bank runs, financial institution restructuring, or sovereign debt restructuring.
However, holding physical bullion introduces negative carry. Institutional custody, armed transit, third-party assays, and comprehensive Lloyd’s of London underwriting typically consume between 20 and 50 basis points (0.20%–0.50%) annually. Furthermore, under IRS Section 408(m), physical bullion held over one year is taxed at the punitive 28% collectibles capital gains rate rather than the standard 15%–20% long-term capital gains rate.
Sovereign Treasury Bills: The Real-Yield Cash Engine
US Treasury Bills (maturing in 4, 13, 26, or 52 weeks) are backed by the full faith, credit, and taxing authority of the United States government. In a positive real interest rate regime where headline T-Bill yields (4.50%–4.90%) comfortably exceed the Consumer Price Index (CPI), T-Bills provide compound nominal expansion without duration volatility.
A critical advantage of Treasury Bills is their statutory exemption from state and local income taxes under 31 U.S.C. § 3124. For corporate entities and individual allocators residing in high-tax jurisdictions (e.g., California, New York, or New Jersey), this exemption elevates the effective taxable-equivalent yield by 40 to 75 basis points above comparable commercial bank CDs.
3. The Barbell Capital Preservation Framework
Empirical portfolio analysis across 5-year rolling windows demonstrates that treating physical bullion and sovereign debt as mutually exclusive assets creates suboptimal risk-adjusted outcomes. An allocator holding 100% T-Bills remains vulnerable to severe currency debasement if inflation outpaces sovereign yields, while an allocator holding 100% gold suffers substantial opportunity cost from foregone compounding yield and vaulting expenses.
Analytical Verdict: The 70/30 Defensive Barbell
For liquid balance sheet defense over a 5-year horizon, an empirical barbell strategy deploying 70% in staggered 3-month to 6-month US Treasury Bills and 30% in allocated, segregated physical bullion delivers superior risk-adjusted preservation. The 70% Treasury allocation generates steady, state-tax-free income that completely offsets the carrying cost of the bullion while providing immediate operational liquidity; the 30% gold allocation insulates the aggregate balance sheet against systemic currency debasement and geopolitical fragmentation.
Frequently Asked Questions
What is the primary difference between allocated and unallocated gold?
Allocated gold means you hold legal title to specific, numbered physical bars stored in a segregated vault. Unallocated gold is an unsecured creditor claim against a bank or dealer’s general balance sheet; if the custodian fails, unallocated holders rank alongside general unsecured creditors.
Are US Treasury Bills subject to state and local income taxes?
No. Under federal statute (31 U.S.C. § 3124), interest earned on US Treasury obligations (T-Bills, Notes, and Bonds) is completely exempt from state and local income taxes, though it is subject to federal income tax.
How does inflation affect the performance of Treasury Bills vs. Gold?
Gold historically appreciates during unexpected inflation surges and severe monetary debasement. Treasury Bills provide protection against moderate inflation only when their nominal yield exceeds the inflation rate (positive real yield); if inflation rises above the T-Bill yield, purchasing power erodes.
What is the tax rate on profits from selling physical gold?
In the United States, profits on physical gold held longer than one year are taxed as ‘collectibles’ at a maximum federal rate of 28%, which is higher than the standard 15% or 20% long-term capital gains tax rate applied to stocks and ETFs.