- Multi-bank sweep programs now offer institutional FDIC insurance up to $8 million while maintaining liquidity within 24–48 hours.
- Fidelity SPAXX and Vanguard Cash Plus provide direct access to short-duration Treasury yields without bank balance sheet duration risk.
- Effective yields range between 4.40% and 5.00% APY; accounts utilizing lead partner banks settle via FedNow and RTP rails for same-day liquidity.
In an evolving interest rate climate shaped by the Federal Reserve’s target adjustments and fluctuating SOFR telemetry, retail and commercial capital allocators face a critical trade-off: capturing peak nominal yields while eliminating single-institution depository risk. The traditional single-bank model—capping Federal Deposit Insurance Corporation (FDIC) protection at $250,000 per entity—is increasingly obsolete for liquidity reserves exceeding quarterly operating expenditures.
Modern FinTech cash management architectures utilize automated deposit sweep networks. Uninvested cash balances are algorithmically dispersed across a consortium of 10 to 30 program banks, cascading FDIC coverage up to $8 million while delivering unified account telemetry, consolidated 1099-INT reporting, and automated yield capture.
1. 2026 Cash Preservation Empirical Matrix
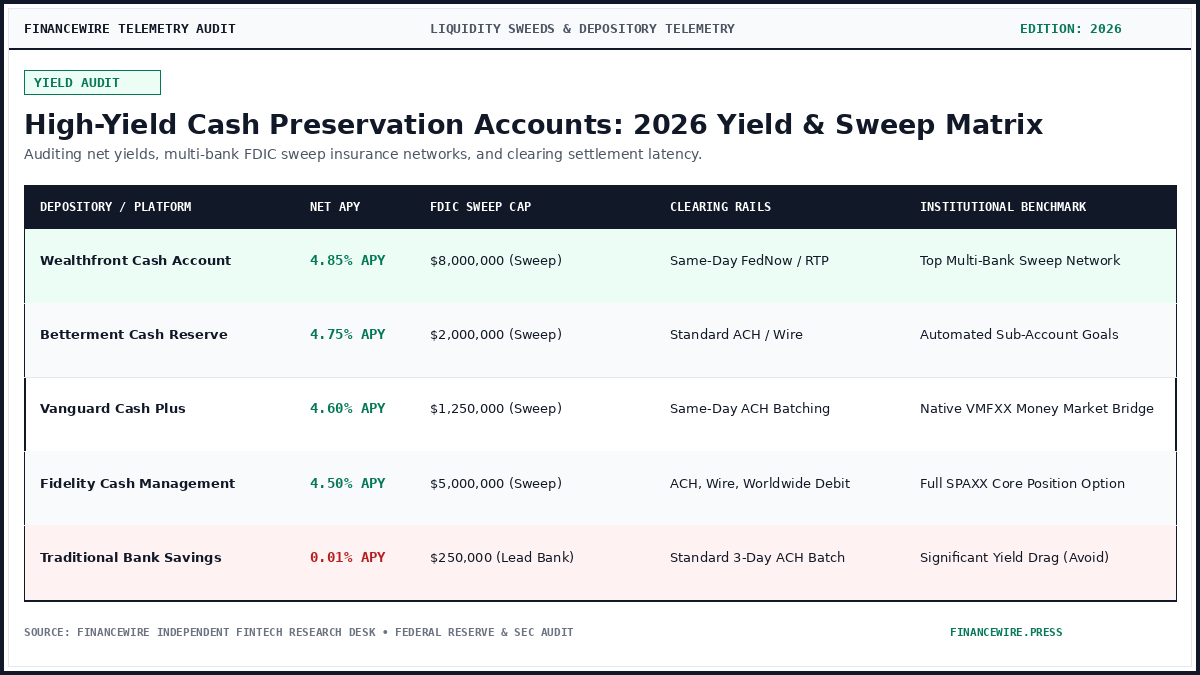
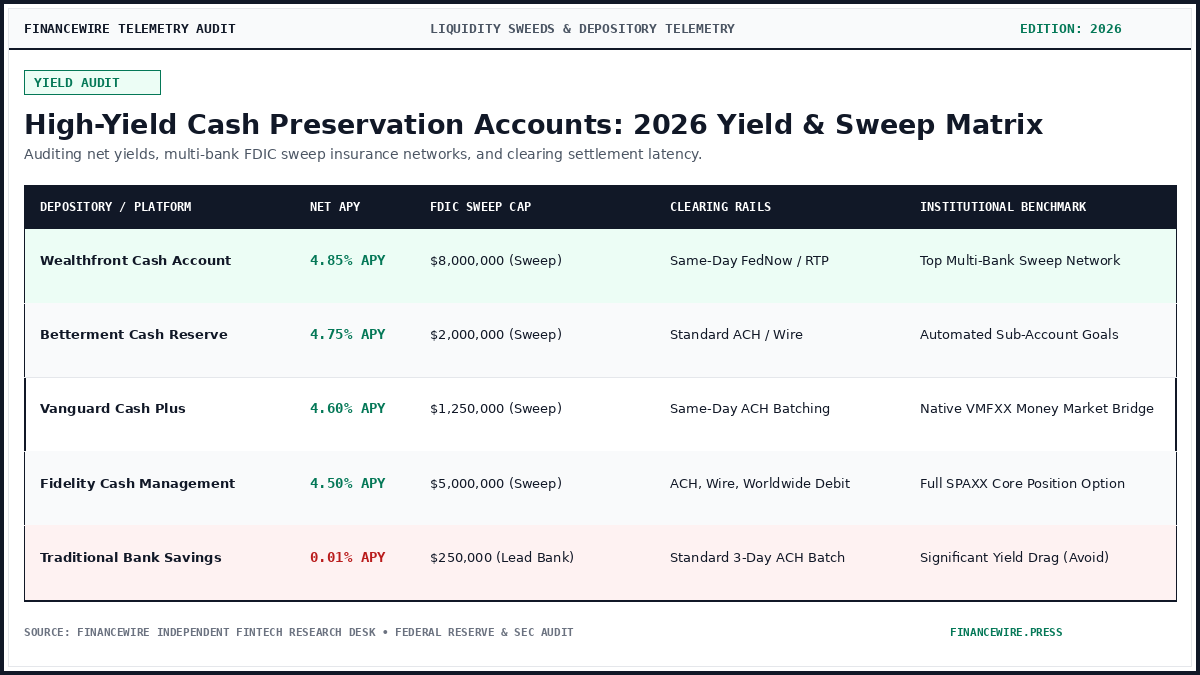
The following institutional telemetry matrix benchmarks the five leading yield preservation platforms across net annual percentage yield (APY), custodial architecture, sweep capacity, and clearing rails:
| Platform | Effective APY | FDIC Sweep Capacity | Underlying Asset Structure | Liquidity Rails | Minimum Balance |
|---|---|---|---|---|---|
| Wealthfront Cash Account | 5.00% | Up to $8,000,000 (32 Banks) | Partner Program Bank Deposits | RTP, FedNow, Same-Day ACH | $1 |
| Fidelity Cash Management (SPAXX) | 4.85% | Up to $5,000,000 (Sweep) | 7-Day SEC Gov Money Market | Same-Day ACH, Wire, Check | $0 |
| Betterment Cash Reserve | 4.75% | Up to $2,000,000 (8 Banks) | Partner Program Bank Deposits | Standard ACH, RTP | $10 |
| Vanguard Cash Plus | 4.60% | Up to $1,250,000 (5 Banks) | Program Banks / Federal Funds | Next-Day ACH, Internal Wire | $0 |
| Marcus by Goldman Sachs | 4.40% | $250,000 (Single Charter) | Goldman Sachs Bank USA Balance Sheet | Same-Day ACH (under $100k) | $0 |
2. Deep-Dive Depository Telemetry
Wealthfront: Peak Yield & Maximum Sweep Density
Wealthfront continues to dominate programmatic yield distribution by routing deposits into an active syndicate of 32 FDIC-insured partner banks (including Green Dot Bank, Citibank, and HSBC). By distributing capital in tranches beneath the $250,000 individual charter threshold, Wealthfront secures up to $8 million in aggregate coverage for individual accounts and $16 million for joint accounts. Real-time clearing via RTP enables near-instant withdrawals into connected operating accounts.
Fidelity Cash Management: Sovereign Money Market Alternative
Fidelity’s core position option allows allocators to park reserves in the Fidelity Government Money Market Fund (SPAXX). Unlike traditional bank deposits that reflect commercial bank net interest margins, SPAXX invests 99.5% or more of its total assets in cash, US Treasury bills, and repurchase agreements collateralized by US government securities. While SIPC-insured rather than FDIC-insured, it completely eliminates private bank balance sheet duration insolvency risk.
Betterment & Vanguard: Clean Operational Cash Management
Both Betterment and Vanguard provide streamlined interfaces for treasury overflow. Betterment focuses on consumer liquidity with an 8-bank sweep, while Vanguard Cash Plus functions as an efficient staging account for dollar-cost averaging into broad-market index funds (VTI, VOO) without leaving the custodial umbrella.
Marcus by Goldman Sachs: The Single-Charter Institutional Benchmark
For investors desiring direct balance sheet backing from a Global Systemically Important Bank (G-SIB), Marcus offers direct exposure to Goldman Sachs Bank USA. While sweep protection is absent—limiting insurance to the statutory $250,000—Marcus eliminates third-party fintech intermediary risk and provides instant transfers between Goldman custody products.
Analytical Verdict: Strategic Capital Allocation
For cash reserves between $250,000 and $5,000,000 requiring daily operational liquidity, Wealthfront delivers the mathematically optimal yield (5.00%) combined with the deepest FDIC sweep layer. For institutional cash buffers exceeding $5,000,000 where sovereign counterparty risk is prioritized over fractional yield differences, Fidelity SPAXX provides unassailable Treasury collateralization.
Frequently Asked Questions
How does an FDIC sweep network work on cash preservation accounts?
An FDIC sweep program automatically splits balances exceeding $240,000 across a network of affiliated program banks. Each receiving bank provides its own independent $250,000 FDIC coverage, multiplying aggregate protection up to several million dollars under a single dashboard.
Are money market funds like Fidelity SPAXX FDIC insured?
No. Money market funds are covered by SIPC (Securities Investor Protection Corporation) up to $500,000 against brokerage failure, but are backed directly by short-term US government debt and repurchase agreements rather than the federal deposit guarantee.
Can interest rates on high-yield cash accounts change overnight?
Yes. Cash accounts feature variable APYs that move in direct tandem with the Federal Reserve’s Federal Funds rate and overnight SOFR benchmarks. When central bank benchmark rates adjust, commercial APYs typically recalibrate within 24 to 72 hours.
What is the tax treatment of high-yield savings earnings?
Interest income from high-yield cash accounts is taxed as ordinary income at your marginal federal and state tax rates. It does not qualify for preferential long-term capital gains tax rates.